Currently Empty: $0.00
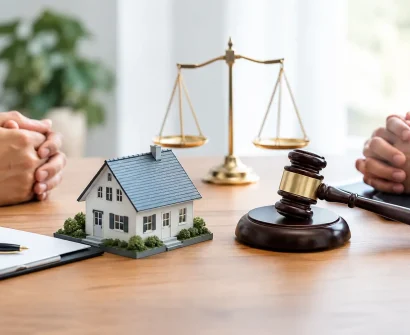
A foreclosure notice can make every piece of mail feel final. It is not final just because the lender says a sale is scheduled. In mediation versus foreclosure sale, the critical question is not which one sounds less frightening. The question is whether mediation gives you a real, documented opportunity to stop, delay, modify, or resolve the foreclosure before the legal process reaches the auction block.
Mediation is a process for negotiation. A foreclosure sale is an event that can transfer your property. They are not equal alternatives, and confusing them can cost you time you do not have.
Mediation Versus Foreclosure Sale: The Basic Difference
Foreclosure mediation usually brings the homeowner, lender or loan servicer, and a neutral mediator into a structured discussion. Depending on your state and court program, the lender may be required to send a decision-maker or provide financial documents, account records, loss-mitigation information, and a reason for any denial. The mediator does not decide who wins and cannot force the lender to approve a modification.
A foreclosure sale is where the property is offered for sale under the rules of your state. In a judicial foreclosure, that sale often follows a lawsuit, court filings, and a judgment. In a nonjudicial foreclosure, the process may move through recorded notices and statutory deadlines without a traditional lawsuit. The exact path matters because your deadlines, hearing rights, and available defenses may be very different.
Mediation can create space for a solution. A sale can end your ability to keep the home, although some states provide redemption rights or other post-sale remedies. Do not assume those rights exist, and do not assume they will be easy to use.
What Mediation Can Actually Do
People often hear “mediation” and picture a calm meeting where everybody works something out. That is not how it always goes. The lender’s representative may have limited authority. The servicer may demand a complete financial package. The meeting may reveal that the lender has already denied relief based on income, documentation, property value, or investor rules.
Still, a well-prepared mediation can force the conversation onto the record and expose whether the lender followed the required process. It may create an opening for a loan modification, repayment plan, reinstatement quote, forbearance, short sale, deed in lieu of foreclosure, or a negotiated time to move. Which option makes sense depends on whether you can afford the home going forward and whether preserving ownership is realistically possible.
Mediation can also give you information. You may learn the claimed default amount, the fees added to your account, the party asserting authority to enforce the loan, and the status of your loss-mitigation review. Those facts can matter in court. But mediation is not a substitute for filing a timely answer, opposition, motion, or request for a hearing when one is required.
The hard truth: mediation does not automatically stop the sale. Some programs pause foreclosure activity while mediation is pending. Others do not. Some require you to request mediation by a strict deadline. Others only become available after the lender files suit or sends a particular notice. Read the notice, local court rules, and state statutes closely. The deadline is part of the case.
What a Foreclosure Sale Changes
Once a sale occurs, your position usually becomes harder. The buyer may be the lender through a credit bid, or it may be a third party. The sale may still need court confirmation in some jurisdictions, while other states treat the completed auction as a major cutoff point.
A scheduled sale is not merely a date on a calendar. It is a procedural deadline that can change leverage. Before the sale, a homeowner may still be seeking loss mitigation, challenging the foreclosure, curing the default, negotiating a payoff, or asking the court for relief. After the sale, the fight may shift to setting aside the sale, redemption, possession, eviction, or a deficiency claim. Those are different disputes with different standards.
That is why waiting to “see what happens” is usually the weakest strategy. If the lender has set a sale date, identify the exact date, time, location, recording reference, case number, and trustee or sheriff involved. Then compare that information against every pending application, hearing, motion, mediation request, and court order in your case.
Do Not Let Mediation Become a Delay Tactic Against You
A lender may tell you that your application is under review. That statement can be meaningful, but it is not the same as a written agreement to postpone a sale. Ask for written confirmation of the review status, missing documents, deadline extensions, and any scheduled sale postponement.
Keep a clean record. Save notices, envelopes, emails, portal screenshots, fax confirmations, payment receipts, and notes from calls. Write down the date, time, department, representative name, and what you were told. If you later need to explain events to a mediator or judge, a folder of documents is stronger than a memory of a frustrating phone call.
Be equally careful with your own submissions. If the servicer requests bank statements, tax returns, pay stubs, a hardship letter, or a financial worksheet, submit exactly what is requested by the deadline and retain proof. An incomplete package may give the servicer a reason to close the review. That does not automatically mean the closure was proper, but it does mean you need the paperwork to challenge it intelligently.
When Court Action May Matter More Than Mediation
Mediation addresses settlement. It does not necessarily resolve legal defects in the foreclosure case. If the lender filed a judicial foreclosure, you may need to respond to the complaint and preserve defenses before the response deadline. A mediation session does not erase that obligation unless a court order or governing rule clearly says otherwise.
Possible issues vary sharply by state and facts. They can include whether the plaintiff has standing, whether required notices were sent, whether the claimed amount is accurate, whether the loan documents and assignments support the claim, whether servicing rules were followed, or whether the lender complied with a mediation order. Do not copy arguments from the internet just because they sound powerful. A court filing needs facts, applicable law, evidence, and proper timing.
If you are representing yourself, start with the case docket or foreclosure notices. Identify what has been filed, what order is in effect, and what deadline comes next. Then build your response around the actual record. Pro Se Legal School teaches self-represented litigants to stay in control of that process with structured documents and filing instruction, not empty promises that a single argument will make a foreclosure disappear.
A Practical Decision Point Before the Sale Date
Ask yourself two direct questions. First, is keeping the home financially possible if the loan is modified or reinstated? Second, is there a live legal or procedural issue that needs to be raised before the sale?
If the answer to the first question is yes, mediation may be worth pursuing aggressively, with a complete financial package and a clear proposal. If the answer to the second is yes, mediation may need to run alongside court action rather than replace it. If keeping the home is no longer realistic, mediation may still help you negotiate time, reduce uncertainty, or explore an orderly exit.
There is no prize for acting like the lender’s timeline is reasonable. Foreclosure systems run on notices, deadlines, proof, and procedure. Get organized, verify what is actually scheduled, put your requests in writing, and do not surrender your position simply because the paperwork is intimidating.
This article provides general educational information, not legal advice. Foreclosure law is state-specific, and competent local counsel is worth considering if you can afford it. But whether you hire counsel or proceed on your own, move before the sale date gives you more choices than explaining afterward why you thought mediation had stopped the process.